NZ casinos with Mastercard: checking payment options
 Available in US
A Mastercard listing does not guarantee account access or withdrawals; verify the cashier, settlement currency, limits and conditions before paying.
Table of Contents
- How to verify Mastercard acceptance before depositing
- What a Mastercard casino payment option actually confirms
- New Zealand’s licensing framework and the limits of payment claims
- Deposits, currency display and the amount ultimately received
- Prepaid cards, PaysafeCard and what cannot be assumed
- Card deposits, withdrawal approval and the separate payout route
- Real-money balances, withdrawal limits and bonus conditions
- Comparing Mastercard with other payment routes
- Refund fees and the cost of reversing a payment
- Mastercard debit and NZD withdrawal settlement
How to verify Mastercard acceptance before depositing
A Mastercard logo on a casino’s general payments page is a lead, not confirmation that the card can be used from every New Zealand account. Payment availability can depend on the account and may change. A specialist review notes that a method’s availability to New Zealand players can differ between deposits and withdrawals; for a deposit check, the relevant evidence is the option presented to the account at the point funds are added.
Start with the casino’s own cashier while signed in to the account intended for use. Open the deposit area and check whether Mastercard appears among the methods offered for that account. A public page may describe the service broadly, while the cashier presents the options applicable to a particular account. The account-level display is therefore more useful than a logo in promotional material or a generic list of payment brands.
The check should be made before entering card details. If Mastercard is listed, read the accompanying instructions and any eligibility notes before proceeding. Confirm that the listed method is specifically Mastercard, rather than assuming that a general reference to “cards” includes it. If the cashier separates card types or presents different choices, the relevant option is the one explicitly shown for the intended transaction.
Choosing a casino for Mastercard use involves checking the details that matter to you, including the information available about licensing and payouts. Use this list as a starting point and verify payment availability with each operator.
License: Malta Gaming Authority, licence no. MGA/B2C/394/2017 N1 Casino is listed with a Malta Gaming Authority licence, no. MGA/B2C/394/2017.
License: Curaçao Gaming Authority, licence no. OGL/2024/165/0185 BitStarz is listed with a Curaçao Gaming Authority licence, no. OGL/2024/165/0185.
License: Tobique Gaming Commission, licence no. 0000064 Neospin is listed with a Tobique Gaming Commission licence, no. 0000064.
Payout speed: 1-3 business days Lamabet’s stated payout speed is 1–3 business days.
License: Tobique Gaming Commission, licence no. 0000091 7Bit Casino is listed with a Tobique Gaming Commission licence, no. 0000091.
License: Tobique Gaming Commission, licence no. 0000002 Ricky Casino is listed with a Tobique Gaming Commission licence, no. 0000002.
License: 07017519840 · Payout speed: 1-3 business days Zotabet is associated with licence reference 07017519840. Its stated payout speed is 1–3 business days.
License: Malta Gaming Authority, licence no. MGA/B2C/370/2017 Play Grand is listed with a Malta Gaming Authority licence, no. MGA/B2C/370/2017.
Payout speed: 1-3 business days Wintino’s stated payout speed is 1–3 business days.
A useful acceptance check records what the cashier actually displays: the payment method’s name, any stated account or card restrictions, and whether the page permits the deposit process to continue to its review stage. This creates a clearer basis for a decision than an old review or a site-wide banner. It does not require sending payment credentials to support or placing a deposit merely to test an uncertain claim.
If Mastercard does not appear, the absence is meaningful for that account at that time. It is not sensible to infer that the casino accepts it simply because another page lists Mastercard, or because the brand is available at a different operator. Nor does a method’s presence in a general New Zealand payment summary establish that it will be offered to every account. The cashier is the practical check, and its contents should be treated as time-sensitive.
Where the cashier is unclear, ask the operator’s support team a narrow question: whether Mastercard deposits are currently enabled for the specific New Zealand account, and whether any stated eligibility condition applies. A broad question about “card payments” may produce a broad answer that leaves the point unresolved. The useful reply names the payment method and confirms the account context. Support should not need a complete card number, security code, online banking password, or one-time login code to answer an availability question.
The distinction between a method being advertised and a method being usable matters particularly when a casino’s information comes from different pages or is not current. A page may remain visible after account options have changed; a review may describe a general service rather than the cashier presented to a particular customer. Neither should override the live account display. If the cashier and written terms appear inconsistent, pause and request clarification before submitting payment details.
Availability should be checked again if the account changes or the casino updates its payment information. An earlier successful deposit does not establish that the same option will remain available indefinitely, and another account’s experience does not settle the status of this one. The check is specific to the account and the time at which the deposit is being prepared.
For people comparing Mastercard casino sites, the same standard applies to each one: verify the option inside the relevant New Zealand account, rather than relying on a general claim that a casino accepts Mastercard. A site that appears to accept cards is not necessarily a site that offers Mastercard to that account. A clean confirmation is an explicit Mastercard listing in the cashier, with no unresolved condition that prevents the deposit.
If the method is not displayed, or support cannot confirm its availability, the sensible result is to treat acceptance as unconfirmed rather than to assume the deposit will work. That avoids turning a broad marketing statement into a financial decision. The final check is simple in principle: use the account-specific cashier, read the conditions attached to the listed method, and obtain a precise answer if the display leaves room for doubt.
Verifying Mastercard Acceptance
Sign in to the intended account and open the deposit area to see which methods are offered specifically for that account.
Confirm that Mastercard is explicitly listed as an option rather than assuming a general reference to “cards” includes it.
Read any accompanying instructions or eligibility notes before entering card details to ensure the method is usable.
Record the method’s name and any stated restrictions displayed in the cashier for a clear basis of decision.
What a Mastercard casino payment option actually confirms
A Mastercard logo in a casino’s payment information confirms a limited point: Mastercard is identified as a payment option in the information being presented. It does not, by itself, confirm that the option will appear for every New Zealand account, that every Mastercard transaction will be accepted, or that the card can receive a withdrawal. Those are separate conditions, not consequences of seeing the brand name.
A specialist review describes Mastercard among the payment options available to New Zealand players, alongside Visa, Visa Electron, Skrill, Trustly, Neteller, iDebit and Apple Pay. That is a report of options, not a guarantee of universal access. Payment availability can depend on the account and may differ between deposits and withdrawals. The useful reading of such a list is therefore narrow: Mastercard is a possible route to investigate, rather than a confirmed feature of every casino account.
The distinction matters because payment descriptions can compress several different stages into one label. A casino may list a method as supported, while the practical question is whether the method is enabled for a particular player and transaction. A card brand on a general page does not establish that the cashier will display it at the relevant point, nor does it establish that the card issuer and payment network will support the proposed transaction. The label names a route; it does not document every condition governing its use.
This is why “Mastercard casino” is not a precise description of a single service. It may refer to a casino that mentions Mastercard in general payment information, one whose cashier offers it for a deposit, or an account where a Mastercard option is actually available. Those descriptions are not interchangeable. A claim about the first should not be read as proof of the second, and a deposit option should not be treated as proof of a payout route.
A Mastercard option also says nothing, by itself, about the complete payment experience. It does not establish the amount that can be transferred, the currency in which a transaction will be processed, or the final amount credited or received. Those details depend on transaction terms beyond the payment-method label. Treating the logo as a complete statement of cost or outcome gives a small piece of information more weight than it can carry.
The same restraint applies to claims about the “best” Mastercard casino online. A payment option is one attribute, not a measure of overall suitability. The label cannot establish the quality of the casino’s terms, the handling of account checks, or the conditions attached to a transaction. A ranking that uses Mastercard availability as though it settled those questions would be measuring a narrow feature and presenting it as a broader verdict.
For a New Zealand player, the sound interpretation is that Mastercard belongs among the payment options reported for this market, while account-level access remains a separate matter. The reported list also includes other card, wallet and payment-service names, but their presence does not imply that each option is available in the same way or under identical conditions. A list records possible methods; it does not prove that every player can use every method for every purpose.
- Treat the cashier display as the primary evidence of availability.
- View Mastercard as a possible route to investigate for your account.
- Keep payment labels separate from payout promises.
- Assume a general logo confirms access for every New Zealand account.
- Infer that a deposit option automatically proves a payout route.
- Treat a general payment summary as a guarantee of universal access.
The word “available” is particularly easy to overread. In a general payment summary, it may describe a method associated with the market rather than a confirmed option on an individual account. It should not be silently expanded to mean “available to all New Zealand customers,” “accepted for every transaction,” or “usable for withdrawals.” Each added meaning requires its own support. Without that distinction, a simple payment label can sound like a broader promise than the information warrants.
Nor does the label settle whether a particular Mastercard is eligible. The brand name does not specify the card’s type, the issuer’s handling of the transaction, or the account conditions that may affect access. It identifies the payment family, not every operational detail. A casino’s general reference to Mastercard therefore cannot be treated as an approval of a specific card or transaction.
The practical value of the label is still real: it narrows the possibilities and indicates that Mastercard has been reported as an option for New Zealand players. Its limit is equally clear. It is an indication of potential availability, not an account-specific confirmation and not evidence of payout support. Keeping those meanings separate makes the payment information useful without turning a logo into a promise.
New Zealand’s licensing framework and the limits of payment claims
A Mastercard symbol on a casino cashier describes a payment option, not the operator’s regulatory position. The two questions belong to separate systems: whether a payment route is offered to a particular account, and whether the casino is operating within New Zealand’s licensing framework. An affirmative answer to one does not establish the other.
New Zealand’s legal position has changed with the Online Casino Gambling Act 2026, which came into force on 1 May 2026. It creates the country’s first domestic licensing regime for online casino gambling. Before that law took effect, online casino services supplied from offshore were not licensed or supervised by a New Zealand regulator. Customers who wagered with those sites had no domestic government recourse.
The Gambling Act 2003 had also prevented online casinos from being based within New Zealand. That restriction did not amount to domestic supervision of offshore websites. The distinction matters: a site accepting New Zealand customers, including customers using Mastercard, was not thereby operating under a New Zealand online-casino licence during the earlier period.
Separate regulatory and licensing functions
The Department of Internal Affairs (DIA) is New Zealand’s primary gambling regulator and oversees regulation of the online casino licensing framework. The Gambling Commission has a distinct role within that framework. It hears and determines casino licensing applications, issues online casino licences and approves changes to licence conditions.
These responsibilities should not be collapsed into a generic claim that an operator is “regulated”. The DIA’s oversight of the framework is not the same function as the Commission’s decision on an application or a change to a licence. A payment page cannot establish either outcome. Nor does a casino’s use of familiar card branding show that its services are covered by a New Zealand licence.
The framework is being introduced in stages. The transitional window began on 1 May 2026 and runs until 1 December 2026. During that period, online casinos that were already providing services to people in New Zealand before 1 May may continue operating under the Act’s transitional provisions. This is a time-limited permission for qualifying existing providers, not proof that every casino available to New Zealand customers has been licensed.
Licensing Timeline
The transitional window for online casinos in New Zealand runs from 1 May 2026 until 1 December 2026, with the full licensed regime expected by 2027.
The full licensed regime is not expected to be operational until 2027. Providers that have not applied for a licence must cease conducting online casino gambling in New Zealand by 1 December 2026. If an application is declined, the provider must stop its online casino operations in the country and leave the market. Unlicensed operation is expected to become an offence from around mid-2027. Those stages make the date of a claim material: “available in New Zealand” and “licensed in New Zealand” are not interchangeable descriptions.
What a payment claim can and cannot establish
A casino may describe Mastercard as an available way to fund an account. That statement concerns payment functionality. It does not establish that the operator has a New Zealand licence, that an application has been approved, or that the operator falls within the transitional provisions. The same limitation applies to claims about Mastercard withdrawals: a card logo is not evidence of licensing status, and licensing status does not by itself confirm that Mastercard can receive a payout.
The legal framework is therefore relevant to comparisons of casino services, but it should not be inferred from the cashier. A payment method can be presented to a New Zealand customer while the operator’s legal position depends on when it began serving the market and whether it meets the applicable transition conditions. Conversely, a regulatory description tells nothing by itself about which payment options appear for an individual account.
Claims about a “licensed casino” need to be read with the regime’s stage in mind. During the transition, an eligible provider may be permitted to continue under transitional provisions without that permission being equivalent to a completed licence issued under the full regime. The Gambling Commission’s role in determining applications and issuing licences is distinct from the temporary continuation allowed for qualifying providers. A broad badge or payment label cannot substitute for that distinction.
For the same reason, a list of casinos accepting Mastercard is not a licensing register. It may describe payment availability, but it cannot answer whether a provider is within the transition, has applied for a licence, or has received a licensing decision. Regulatory claims and payment claims require separate evidence and should remain separate in any comparison.
Deposits, currency display and the amount ultimately received
A Mastercard deposit has two separate monetary records: the amount charged to the card and the amount added to the casino balance. Those figures can be expressed in different currencies. If the card transaction is processed in a currency other than the card account’s currency, conversion may affect the amount charged. The balance shown after the deposit is therefore not, by itself, a complete record of the card-side cost.
The same distinction applies in reverse when funds leave the casino. A balance displayed in NZD identifies the currency used for that display; it does not establish the currency in which a later withdrawal will be settled. A specialist casino review notes that exchange rates or conversion margins can affect the amount ultimately received. That is a conditional cost, not a fixed deduction: its effect depends on the currencies involved and the conversion applied.
Attention A displayed NZD balance does not guarantee that the original deposit amount will return unchanged in NZD due to potential conversion margins or exchange rates.
For a Mastercard deposit at an online casino, the useful comparison is not simply “amount deposited” against “balance shown”. The relevant chain is the card charge, the credited balance, and—when funds are paid out—the currency and amount received. Each is a separate figure. A clean-looking NZD balance can coexist with a later conversion, so the display should not be treated as a promise that the original amount will return unchanged in NZD.
A practical record keeps those stages distinct. The card statement shows the transaction charged to the card; the casino account shows the credited balance; the payment terms identify the currency used for settlement. If a statement or account record shows a difference, the currency labels help identify whether the gap relates to conversion rather than to the balance arithmetic itself. A displayed figure without its currency is incomplete information.
This matters when comparing a Mastercard deposit with a promotional offer as well. A bonus may change the balance displayed, but it does not establish the currency of a later payment or remove any conversion exposure. The promotional balance and the cash deposited should not be treated as interchangeable amounts. The relevant figure for a money comparison is the amount that can ultimately be paid, in the currency in which it is settled.
The distinction is especially important where the casino interface defaults to NZD. A convenient display can make balances easier to read, but it does not settle how a payment is converted. Nor does the currency shown beside the balance prove which exchange rate or margin will apply. Those details belong to the payment terms and transaction record, rather than to the number on the account screen.
The accounting is straightforward even when the currencies are not: the deposit credit is one entry, the displayed balance is another, and the amount received after any conversion is the final figure that matters. Treating those as separate values avoids mistaking a NZD label for a guarantee of NZD settlement.
Prepaid cards, PaysafeCard and what cannot be assumed
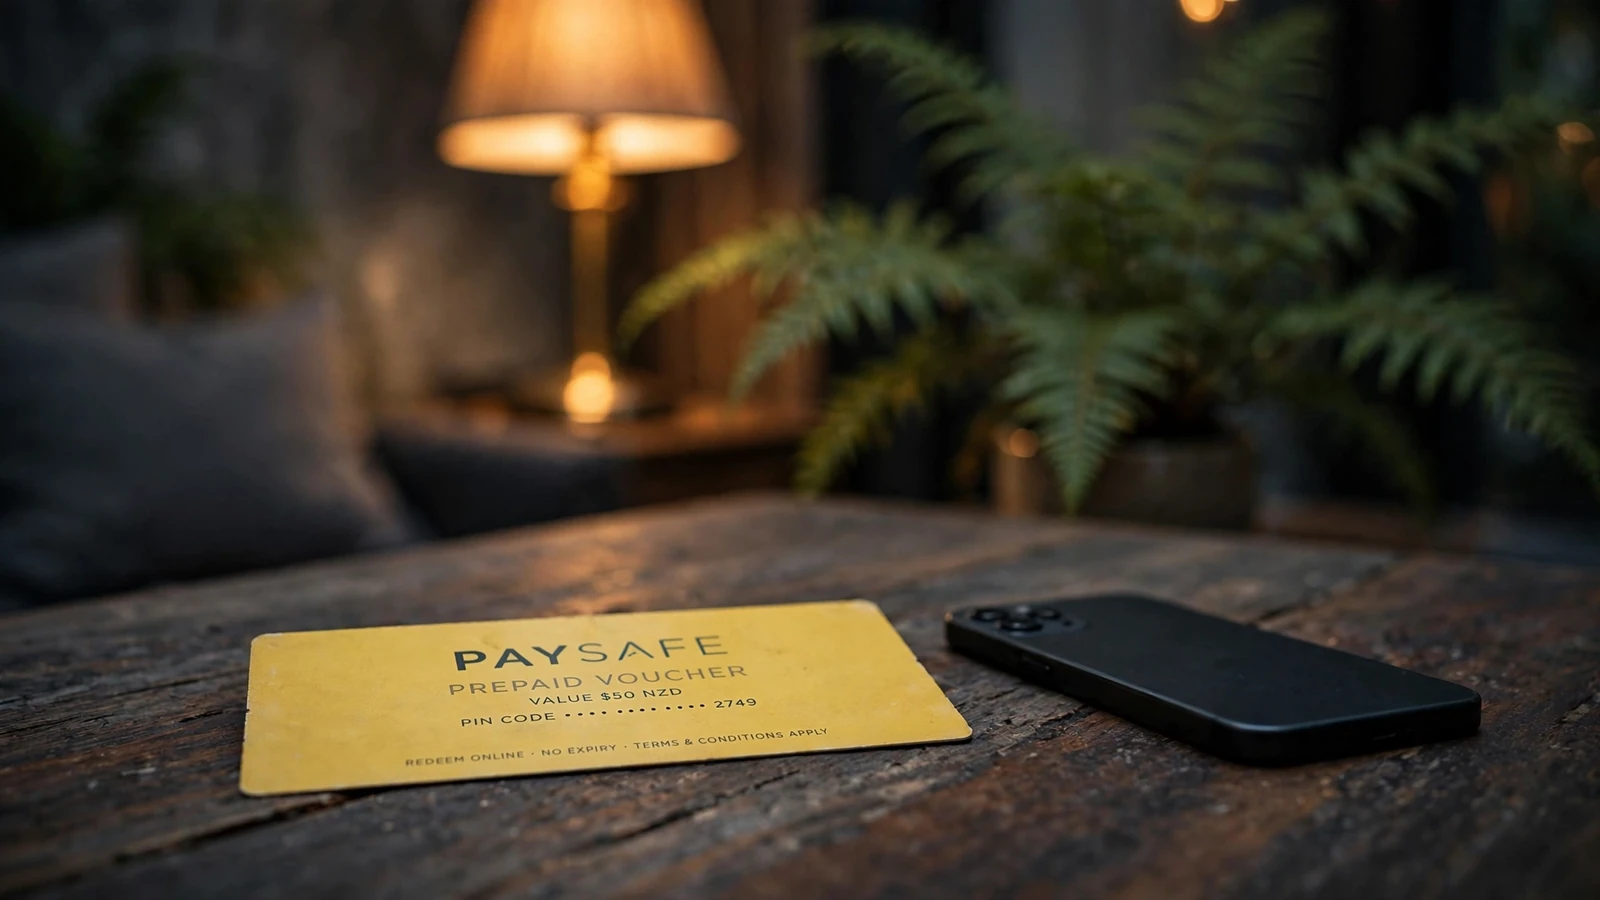
PaysafeCard and a prepaid Mastercard are separate payment products. Seeing one named in a casino cashier does not establish that the other will work there. Both may be described casually as prepaid options, but that resemblance is not evidence of shared acceptance.
A specialist review reports that some casino cashiers serving New Zealand accounts accept PaysafeCard deposits. That is a limited observation, not a market-wide condition: availability needs to be confirmed for an eligible New Zealand account. A payment option described in a general review may not be offered to every account, so the cashier’s available methods are more relevant than a broad claim.
The distinction matters when the cashier lists PaysafeCard but not Mastercard, or lists Mastercard without identifying prepaid cards as supported. A prepaid Mastercard runs through card-payment arrangements; PaysafeCard is a different method. Acceptance of one does not prove acceptance of the other, and a general statement that a casino accepts Mastercard does not settle whether it accepts a particular prepaid card.
The same boundary applies to winnings. PaysafeCard being available for a deposit does not establish that it can receive casino withdrawals. Nor does a successful deposit with a prepaid Mastercard confirm that the card can be used as a destination for funds paid out by the casino. Deposit acceptance and payout capability are distinct functions; the label on a deposit option answers only the first.
A separate payment product that may be accepted for deposits but does not guarantee withdrawal capability.
A card-payment arrangement that is distinct from PaysafeCard; its acceptance is not guaranteed by the presence of other prepaid options.
The primary card brand; its availability for deposits does not automatically confirm support for prepaid versions or payouts.
A prepaid product can therefore appear useful for putting funds into an account while offering no evidence about how money could later be returned. Treating the product name as proof of both directions collapses two separate decisions into one. The cashier’s available deposit methods and its stated withdrawal arrangements need to be considered separately.
For PaysafeCard, the defensible claim is narrow: a specialist review has reported deposit acceptance at some New Zealand casino cashiers, subject to confirmation for an eligible account. That does not support a blanket claim that New Zealand casinos accept PaysafeCard, that every account can use it, or that prepaid Mastercard is accepted wherever Mastercard appears. It also does not make PaysafeCard a destination for winnings. The payment name is not a complete account of the transaction.
Card deposits, withdrawal approval and the separate payout route
A Mastercard deposit and a casino withdrawal are separate stages of a transaction. The card may be used to fund an account without being an eligible destination for winnings. A card logo beside a deposit option therefore says nothing conclusive about how a later payment will be sent, including where a gift card is involved.
A specialist review describes the withdrawal process as beginning only after the casino approves the request. The transfer to an external payment provider or account cannot start before that decision. Approval is a separate step from submitting a withdrawal request, so the time shown for a payment route would not, by itself, represent the full time from request to receipt.
Identity verification is part of the withdrawal process: proof of identity must be provided before a withdrawal can be processed. The casino may also need to complete payment checks, and any applicable bonus conditions can affect whether a request is ready for approval. These checks can add time before the transfer begins. The distinction matters in any estimate: casino review comes first, followed by the external payment process.
The payment route may also change between deposit and withdrawal. A specialist review notes that when the original deposit method cannot receive payouts, the casino may require a separate destination, such as a bank account, digital wallet or cryptocurrency address. That possibility does not mean every casino permits each of those routes for every account. The available destination and any required account details depend on the casino’s process.
A practical record of the transaction should therefore distinguish three things: the method used to deposit, the casino’s approval of the withdrawal, and the destination used for the external transfer. Treating these as one continuous card payment can obscure where a delay or a change of route occurs. A Mastercard deposit does not, on its own, establish that the casino will return funds to that card.
Nor does the existence of a card deposit option establish what would happen if a card payment were disputed or reversed. The relevant withdrawal process is not a promise of card payout support, and it should not be confused with the separate rules governing a card dispute. For a withdrawal, the operative details are the casino’s approval, completion of identity and payment checks, and confirmation of an eligible destination. If those steps point to a different route, the withdrawal is not simply a refund to the original card.
Withdrawal Process
- Casino approval of the request must occur before funds are transferred to a provider.
- Identity verification and payment checks are mandatory steps before processing.
- The payout route may differ from the deposit method if the original card is ineligible.
- Total processing time includes both casino review and external payment transfer.
Real-money balances, withdrawal limits and bonus conditions
A balance shown in an online casino is not necessarily the amount available for withdrawal. The relevant figure is the portion that remains payable after account conditions, withdrawal caps and any bonus rules have been applied. A Mastercard deposit does not change those calculations: the card identifies a funding route, not an entitlement to cash out the full displayed balance.
A specialist review describes withdrawal limits that may apply per transaction or across daily, weekly or monthly periods. The casino’s terms and the payment provider’s rules can both affect the amount released, so a permitted casino withdrawal may still be constrained by the route’s own cap. Larger transfers may also receive additional review, according to the same type of review. That can affect when a request is handled; it does not, by itself, establish that the balance has been reduced.
The practical calculation is therefore not just the account balance minus the amount requested. Any applicable cap determines what can be submitted or paid within the relevant period, while a review can delay release of a larger transfer. The precise conditions depend on the casino and provider terms in force for the account. A headline limit without its period or scope is incomplete: a per-transaction cap and a monthly cap constrain funds in different ways.
Bonus-related funds require a separate check. A specialist review notes that winnings connected with a bonus may carry wagering requirements, restrictions on which games count and how much they contribute, maximum-bet rules, expiry dates, or a maximum cashout. Each condition can change the withdrawable amount or the point at which a request becomes available. A displayed total that includes bonus winnings should therefore not be treated as entirely payable until the applicable conditions have been met.
The final amount is best understood as the balance eligible under the account terms, reduced by any relevant withdrawal cap or bonus cashout condition. If a bonus has expired, a game has contributed differently than expected, or a maximum cashout applies, the account display alone may not show the final payable figure. For real-money play funded by Mastercard, the useful distinction is between money visible in the balance and money that satisfies the casino’s withdrawal conditions.
Comparing Mastercard with other payment routes
Mastercard sits alongside Visa and Visa Electron among the card options described as available to New Zealand players. The same payment overview includes Skrill, Trustly, Neteller, iDebit and Apple Pay. That is a list of payment types, not a statement that every casino account can use every option or that each route handles both deposits and payouts.
The practical distinction is how funds may move after a casino releases them. Digital wallets and cryptocurrencies may transfer funds rapidly once the casino has released a payment. That describes the transfer stage, not the time spent waiting for casino approval. A specialist payment review also characterises bank transfer as a direct route to a New Zealand bank account. Card payouts are different: their availability depends on support from both the card issuer and the payment network. Mastercard’s presence among card options therefore does not, by itself, establish that a payout can be returned to a particular card.
Does a Mastercard logo guarantee I can withdraw funds to my card?
No, a logo confirms it is a payment option, but payout support depends on the card issuer, payment network, and casino terms.
How do digital wallets differ from card payouts?
Wallets and cryptocurrencies may transfer released funds rapidly, whereas card payouts are conditional on issuer and network support.
Is a bank transfer the same as a card payout?
No, a bank transfer is a direct route to a New Zealand bank account, while card payouts rely on the specific card’s compatibility.
For a route comparison, the relevant question is not simply whether a logo appears beside a cashier option. It is whether the named method suits the intended transaction. A card can be considered alongside Visa, while a wallet or cryptocurrency represents a different transfer route and a bank transfer directs funds to a bank account. The general descriptions do not make these routes interchangeable, nor do they establish a common processing speed.
The distinction matters most when comparing a deposit route with a way to receive funds. Wallets and cryptocurrencies may move released funds rapidly; bank transfers provide a direct bank-account route; and card payouts remain conditional on issuer and network support. Those characteristics describe the route after release, not a guarantee about account-specific access. A payment method can be relevant to a comparison without being confirmed for every New Zealand account or every transaction type.
Refund fees and the cost of reversing a payment
A reversed Mastercard payment does not necessarily return the original amount intact. A specialist review reports that a payment provider may charge a NZD 12 fee when processing a refund. That is a conditional cost, not a standard fee that can be assumed to apply to every casino or card transaction; the provider’s terms determine whether it is charged.
The calculation is straightforward: if the fee applies, the refunded amount is reduced by NZD 12. The original debit and the refund can therefore differ even when the transaction itself has been reversed. A reversal restores the funds subject to the provider’s processing terms, not necessarily the exact sum first taken from the card.
This matters when comparing Mastercard payment options across online casinos. A displayed deposit method establishes neither that refunds are fee-free nor that the same provider terms apply to every account. The relevant detail is the refund policy attached to the payment route, including whether a provider fee is deducted and how the refund is handled. Those terms should be considered separately from ordinary deposits and casino withdrawals: a refund reverses a payment, while a withdrawal pays out an eligible casino balance.
The fee should not be treated as an automatic deduction from every refund. Equally, the word “refund” alone does not establish that the returned amount will match the original debit. Where the policy is unclear, the net result cannot be calculated reliably from the deposit amount alone. A small line in payment terms can alter the final amount; the label “reversed” does not make that arithmetic disappear.
Mastercard debit and NZD withdrawal settlement
A Mastercard debit card links card transactions to a bank account, but that does not make every debit-card deposit eligible to return to the same card. Card acceptance and payout support are separate functions: a casino can process a card payment without having a compatible route for sending a withdrawal back through that card.
For NZD settlement, a specialist casino review states that the casino permits withdrawals in New Zealand dollars through any banking option it offers. That describes the currency available for withdrawal across those banking routes; it does not establish that every Mastercard debit card is itself a supported payout destination. The distinction matters because “withdrawal in NZD” identifies the settlement currency, while “paid to a Mastercard” identifies a particular destination and payment network.
The debit-card label therefore answers only part of the payment question. A card may be usable for a deposit, while the withdrawal is handled through a banking option instead. The casino’s NZD facility can still apply to that banking route, without changing the status of the card as a payout method.
The relevant terms should be read separately: whether Mastercard debit is accepted for deposits, which destinations are available for withdrawals, and whether the selected banking option can settle in NZD. Treating those as one condition turns a currency statement into a card-payout promise it does not make. For a New Zealand account, the practical result is that NZD withdrawal availability may be broad across banking options, while Mastercard debit payout support remains a distinct capability.
Created by the ”Casino Slots Adviser NZ” editorial team.